First Homes Scheme Mortgages

Buying a Discounted First Home? Expert Mortgage Advice

The First Homes scheme lets eligible first time buyers in England buy a new home for at least 30% below its market value, and in some areas up to 50% less. It is one of the best ways onto the property ladder, but the eligibility criteria, price caps and resale rules catch a lot of people out. Before setting up the business, our founder spent four years as a specialist new build mortgage broker working with government schemes like this every day, so we can tell you quickly whether a First Home is right for you.

★★★★★
Rated 5 stars across Google & Trustpilot.
Get Fee-Free Mortgage Advice Today.
Trusted by thousands of clients .
Smiling bald man with a beard wearing a dark gray shirt in a modern office setting.Smiling woman with long light brown hair wearing a beige cardigan and a pink top in a modern office setting.Man in a navy blue blazer and white shirt smiling in a modern office with glass walls and plants.Smiling woman with light brown hair wearing a navy blazer and white blouse in a modern office setting.
Start from here

How can we help you?

let us know about your circumstances to get your application started

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Moving Home Mortgages
First Time Buyers Mortgages
Buy To Let Mortgage Broker

0

Application to Offer Success Rate

0

Satisfied customers across our trading group

0

Mortgage products across our whole of market panel

What Is the First Homes Scheme?

First Homes is a government scheme in England that sells new build homes to first time buyers at a discount of at least 30% on the open market value. Local authorities can set a bigger discount of 40% or 50% where homes are less affordable. The homes are built on selected developments and sold through the developer, with the local council checking eligibility.

The key point is that the discount stays with the property. When you sell, you must sell to another eligible buyer at the same percentage discount on the market value at the time, so the home stays affordable for future buyers. A legal restriction recording this is registered at the Land Registry.

How Does the First Homes Scheme Work?

Say a new build house has a full market value of £300,000 and the local discount is 30%. You would pay a discounted purchase price of £210,000, and your mortgage and deposit are based on that figure. After the discount has been applied, the price must be no more than £250,000, or £420,000 in London.

You must buy with a mortgage or home purchase plan covering at least half of the discounted price, so you cannot buy a First Home with cash alone. Most major lenders accept First Homes, but they need to be comfortable with the resale restrictions, so lender choice is narrower than on an open market purchase.

The home must be your only or main residence. You cannot let it out, except in limited circumstances agreed with the council.

How Much Deposit Do You Need for a First Home?

Your deposit is based on the discounted price, not the market price. On a £210,000 discounted price, a 5% deposit would be £10,500.

Some lenders accept 5% on First Homes and others want 10%, so the deposit you have can change which lenders are open to you. As a general guide:

First time buyer holding the keys to her discounted First Homes scheme property
  • 5% deposit: accepted by a number of lenders on the discounted price
  • 10% deposit: more lender choice and better mortgage rates
  • Lifetime ISA: you can use a Lifetime ISA towards your deposit if the price is within its limits

We will check which lenders accept First Homes on your chosen development and how much deposit you need, before you pay a reservation fee.

Who Is Eligible for First Homes?

You must be a first time buyer, aged 18 or over, and buying the home as your only or main residence. Your household income must be no more than £80,000 a year, or £90,000 in London. If you are buying with someone else, both of you must be first time buyers.

You also need to be able to get a mortgage for at least half of the price.

Local Eligibility Criteria

Local authorities can set extra local eligibility criteria for the first three months a property is on sale. These might give priority to people with a local connection, key workers or people on lower incomes.

Members of the armed forces, and recent veterans, do not have to meet local connection criteria. After three months the national eligibility criteria apply.

How Much Can You Borrow?

Lenders assess affordability on the discounted price, using your income and outgoings in the usual way. Because the price is lower, your monthly payments are lower too, which can make the difference between passing and failing an affordability assessment.

We check your borrowing with lenders that accept First Homes before you commit to a property.

Eligibility: What Do Lenders Look At?

Lenders that offer First Homes mortgages look at the same areas as any other purchase, plus the scheme paperwork.

Income and Affordability: your household income, outgoings and existing debts.

Credit History: a clean record gives you the widest choice. If you have adverse credit, you could be referred to our sister company, Alexander Southwell Mortgages, as this may fall under the specialist category.

The Scheme Documents: lenders check the discount, the price cap and the legal restriction on future sales.

The Property: most First Homes are new builds, so lenders apply their new build lending criteria too.

You must be a first time buyer, aged 18 or over, and buying the home as your only or main residence. Your household income must be no more than £80,000 a year, or £90,000 in London. If you are buying with someone else, both of you must be first time buyers.

You also need to be able to get a mortgage for at least half of the price.

Local authorities can set extra local eligibility criteria for the first three months a property is on sale. These might give priority to people with a local connection, key workers or people on lower incomes.

Members of the armed forces, and recent veterans, do not have to meet local connection criteria. After three months the national eligibility criteria apply.

Lenders assess affordability on the discounted price, using your income and outgoings in the usual way. Because the price is lower, your monthly payments are lower too, which can make the difference between passing and failing an affordability assessment.

We check your borrowing with lenders that accept First Homes before you commit to a property.

Lenders that offer First Homes mortgages look at the same areas as any other purchase, plus the scheme paperwork.

Income and Affordability: your household income, outgoings and existing debts.

Credit History: a clean record gives you the widest choice. If you have adverse credit, you could be referred to our sister company, Alexander Southwell Mortgages, as this may fall under the specialist category.

The Scheme Documents: lenders check the discount, the price cap and the legal restriction on future sales.

The Property: most First Homes are new builds, so lenders apply their new build lending criteria too.

Buying a First Home: Step by Step

01

Initial Conversation

We check your eligibility, your deposit and your budget, and explain how the discount works.

02

Decision in Principle

We secure a decision in principle with a lender that accepts First Homes, so you can reserve with confidence.

03

Reserving Your Home

You pay the developer's reservation fee and the council confirms you meet the eligibility criteria.

04

Full Mortgage Application

We submit your application on the discounted price with all the supporting documents.

05

Valuation and Legal Work

The lender values the property and your solicitor checks the First Homes restriction and the conveyancing process.

06

Mortgage Offer

Your mortgage offer is issued, usually with a long enough offer period to cover the build.

07

Completion and Keys

The home is finished, your purchase complies with the scheme and you collect the keys to your first home.

Arrow
Arrow

What Are the Costs of Buying a First Home?

‍Reservation Fee: most developers charge a reservation fee to hold your plot.

Stamp Duty: calculated on the discounted price you pay, so first time buyer relief often means little or no stamp duty.

Legal Fees: you need a solicitor who understands First Homes and the Land Registry restriction.

Survey and Valuation: new homes come with a builder's warranty, but you may still want a snagging survey.

Our Advice: fee free. We are paid by the lender when your mortgage completes.

Can I Get a First Homes Mortgage With Bad Credit?

Sometimes. It depends on what is on your credit file and how recent it is. Choice is already narrower on First Homes, so adverse credit can be harder to place.

If you have adverse credit, you could be referred to our sister company, Alexander Southwell Mortgages, as this may fall under the specialist category.

Why Choose Fee Free Mortgage Broker for First Homes?

‍No broker fees. Our advice is free to you because the lender pays us when your mortgage completes.

New build specialists. Our founder Jamie Alexander spent four years as a specialist new build broker and knows the government schemes inside out.

We know which lenders say yes. We check lender appetite for First Homes before you apply.

Help with timings. We make sure your mortgage offer lasts until the build completes.

Know the rules

First Homes Eligibility Criteria, Price Caps and Resale Rules

The First Homes scheme has national eligibility criteria set by the government and local criteria set by each local authority. Here is a plain English summary of the rules that matter most when you buy, and when you come to sell.

National eligibility criteria

First time buyers aged 18 or over, with a household income of £80,000 or less, or £90,000 or less in London, buying the home as their main residence.

The discount

A discount of at least 30% on the market value. Some local authorities set 40% or 50% where local house prices are high compared with local incomes.

Price cap

After the discount has been applied, the purchase price cannot be more than £250,000, or £420,000 in London. Councils can set a lower maximum price.

Mortgage requirement

You need a mortgage or home purchase plan for at least 50% of the discounted price, so you cannot buy with cash or savings alone.

Local criteria

For the first three months, councils can prioritise local residents, key workers or lower income households. Armed forces members and recent veterans are exempt from local connection rules.

Selling a First Home

Future sales must be to eligible buyers at the same percentage discount, based on a valuation by a RICS registered chartered surveyor. The restriction stays on the title at the Land Registry.

Because the discount stays with the home, a First Home suits buyers who want a lower price today and are happy that future buyers get the same deal. If you think you might want to sell at full market value later, it is worth comparing First Homes with shared ownership or a standard new build purchase with a 5% deposit. We can talk through all three with you before you reserve.

Most First Homes are sold on new build developments, so lenders also apply their new build rules on deposits and offer periods. We check both sets of criteria for you, so there are no surprises late in the conveyancing process.

First Homes questions

First Homes Scheme FAQs

The questions first time buyers ask us most about the First Homes scheme.

Is First Homes the same as shared ownership?

No. With First Homes you buy and own the whole property at a discount, and you pay no rent. With shared ownership you buy a share and pay rent on the rest.

Can I sell my First Home at full market value?

Usually not. You sell to another eligible buyer at the same percentage discount. If you cannot find an eligible buyer after a set period, the council may let you sell on the open market, but you would repay the discount percentage to the council.

Is First Homes available in Wales, Scotland or Northern Ireland?

No. First Homes is a scheme for England only. Scotland, Wales and Northern Ireland have their own schemes.

Can I use First Homes with a Lifetime ISA?

Yes. You can use a Lifetime ISA towards your deposit as long as the purchase meets the Lifetime ISA rules.

What about the new Your First Home scheme?

The government has announced a separate equity loan scheme for new build buyers called Your First Home. Full details were still to be confirmed at the time of writing, so speak to us before you reserve anything.

Related guides: first time buyer mortgages · new build mortgages · shared ownership mortgages

Your home may be repossessed if you do not keep up repayments on your mortgage. Fee Free Mortgage Broker is a trading style of Alexander Southwell Mortgage Services Ltd, authorised and regulated by the Financial Conduct Authority, firm reference 1011890.

Written by Jamie Alexander CeMAP, mortgage adviser with 15 years' experience. Last reviewed October 2026.

Speak to a First Homes Mortgage Adviser Today

Found a First Home or want to know if you qualify? Our mortgage advisers will check your eligibility and find a lender that accepts the scheme, with no broker fees to pay.

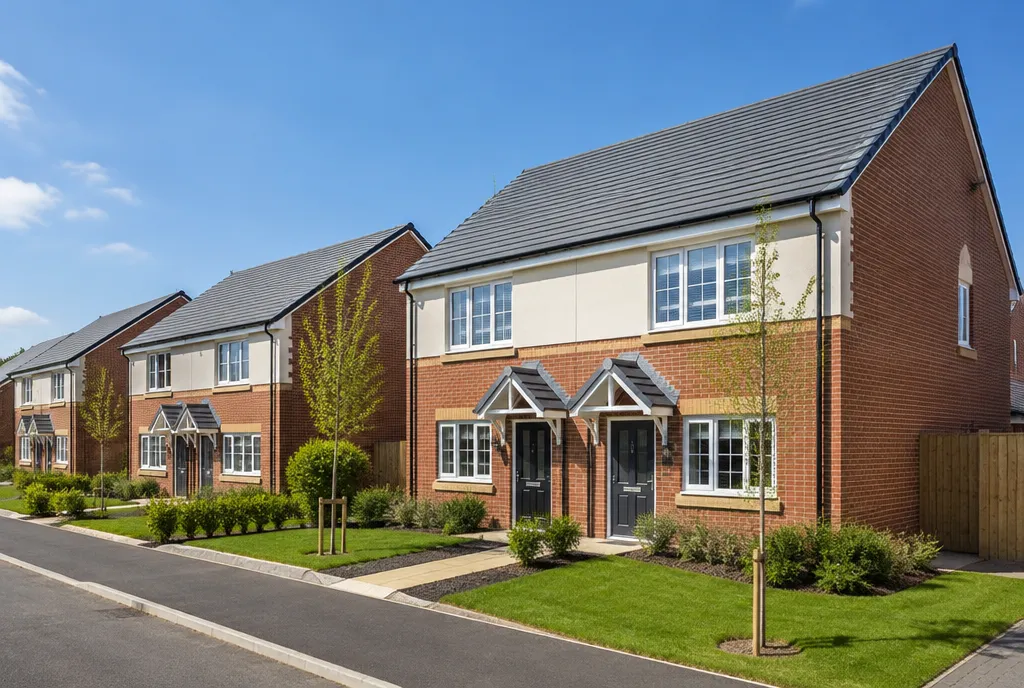
New build semi detached houses on an English development offering First Homes

How can we help?

Get started by letting us know a little bit about what you need

 I want to buy a home 🏘️
I want to remortgage ♻️
BUYING A HOME

What best describes you?

First-time buyer
Home mover
Buy to let
Additional property / second home
Back

Have you found a property yet?

Yes, I’ve had an offer accepted
Yes, still viewing
No, just getting started
Back

How much deposit do you roughly have?

Yes, I’ve had an offer accepted
Yes, still viewing
No, just getting started
Back